- Home
- Tools
- 1099 Generator
- 1099-NEC Generator
1099-NEC Generator: Fill Out Form 1099-NEC for 2026
Form 1099-NEC reports what your business paid a contractor or freelancer for services. This fillable 1099-NEC generator lays your entries out on the December 2026 revision of the form: enter your business, the contractor and what you paid them, and download printable Copy B and Copy 2 with the IRS recipient instructions.
Reviewed by M. Humza. Checked against the IRS sources October 22, 2026. Fill in the form
For businesses issuing 1099-NECs for payments they made. Paid as a contractor? Your 1099 comes from the business that paid you. Not sure which form you need? Compare both in the 1099 generator.
What is Form 1099-NEC?
Form 1099-NEC, Nonemployee Compensation, is the IRS information return a business uses to report pay for services to someone who is not its employee, such as an independent contractor, freelancer or attorney. The business gives the contractor Copy B, files Copy A with the IRS, and the contractor reports the income on their tax return.
Who gets a 1099-NEC, and who does not?
- Gets one: an individual, partnership or LLC taxed as either, to whom you paid $2,000 or more in 2026 for services in your trade or business.
- Attorneys: fees for legal services of $2,000 or more go in box 1a, even when the law firm is a corporation.
- Generally not: corporations, including LLCs taxed as corporations, and payments for personal rather than business services.
- Card and payment network payments: what you paid by card or through a third-party payment network is reported on Form 1099-K by the payment company, not on a 1099-NEC, according to the IRS instructions.
- Employees: wages go on a Form W-2, never a 1099-NEC.
What do I need to fill out a 1099-NEC?
- Your business name, address and telephone number. The phone number is required on the contractor's copy.
- Your TIN: your EIN, or your SSN if you are a sole proprietor without an EIN.
- The contractor's name, address and TIN from their Form W-9. Their copies show only the last four digits.
- The total you paid them in 2026 for services, leaving out anything paid by card or through a third-party payment network, and any tax you withheld.
How do I fill out a 1099-NEC?
- Payer. Your business name, address, phone number and full TIN (EIN, or SSN if you are a sole proprietor without one).
- Recipient. The contractor's name and address from their Form W-9, and the last four digits of their TIN.
- Box 1a. The total you paid them for services in 2026, including any tips in box 1b and overtime in box 1d.
- Box 4. Backup withholding, only if you withheld it, for example because the contractor did not give you a TIN. Form W-9 explains when it applies.
- State boxes. State tax withheld, your state number and state income, if your state requires them.
- Download and send. Give Copy B to the contractor, keep your records, and file Copy A through IRIS.
Example: a 1099-NEC for a bookkeeper paid monthly
Blue Ridge Plumbing LLC in Asheville pays a freelance bookkeeper, Samir Patel, $520.00 a month. Over 2026 that comes to $6,240.00, paid by bank transfer with no tax withheld.
No single fee comes near $2,000, but the minimum applies to the year's total for one person. The total is over the minimum, so the company puts $6,240.00 in box 1a, gives Samir Patel Copy B by February 1, 2027 and files Copy A through IRIS by the same date.
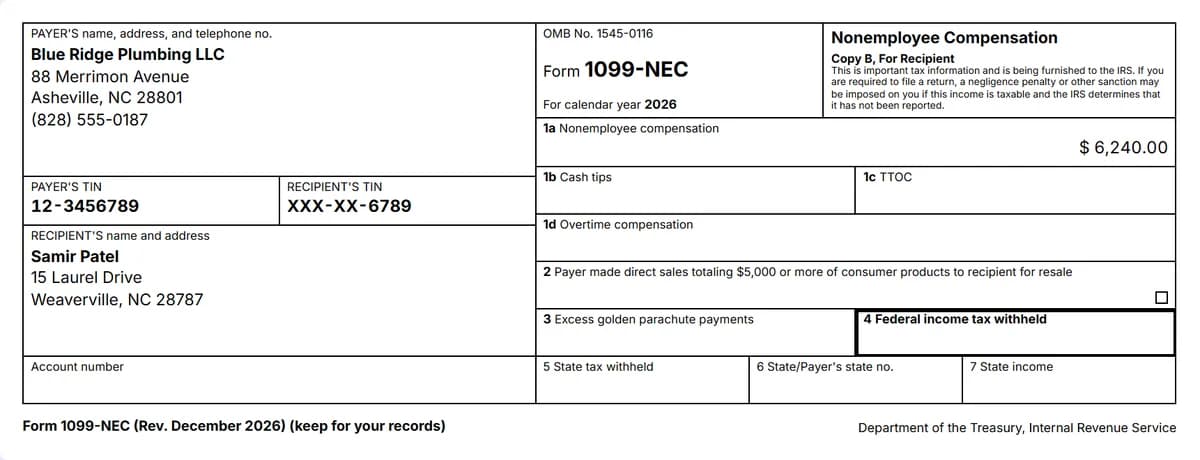
1099-NEC boxes explained
| Box | What goes in it |
|---|---|
| 1a | Nonemployee compensation: fees, commissions and other pay for services by someone who is not your employee. |
| 1b and 1c | Cash tips included in box 1a, and up to two Treasury Tipped Occupation Codes. New for 2026. |
| 1d | Overtime compensation included in box 1a. New for 2026. |
| 2 | A checkbox: payer made direct sales totaling $5,000 or more of consumer products to recipient for resale. |
| 3 | Excess golden parachute payments. |
| 4 | Federal income tax withheld, which for a 1099-NEC means backup withholding. |
| 5 to 7 | State tax withheld, the state and your state ID number, and state income. |
Box captions follow the December 2026 revision of the form. Full rules are in the IRS Instructions for Forms 1099-MISC and 1099-NEC.
What the contractor sees on the back of Copy B
You received this form instead of Form W-2 because the payer did not consider you an employee and did not withhold income tax or social security and Medicare taxes.
If you believe you are an employee and cannot get the payer to correct this form, report the amount shown in box 1 on the line for “Wages, salaries, tips, etc.” of Form 1040, 1040-SR, or 1040-NR. You must also complete Form 8919 and attach it to your return. For more information, see Pub. 1779, Independent Contractor or Employee.
If you are not an employee but the amount in box 1 is not self-employment (SE) income (for example, it is income from a sporadic activity or a hobby), report the amount shown in box 1 on the “Other income” line (on Schedule 1 (Form 1040)).
Recipient’s taxpayer identification number (TIN). For your protection, this form may show only the last four digits of your TIN (social security number (SSN), individual taxpayer identification number (ITIN), adoption taxpayer identification number (ATIN), or employer identification number (EIN)). However, the issuer has reported your complete TIN to the IRS.
Account number. May show an account or other unique number the payer assigned to distinguish your account.
Box 1a. Shows your total nonemployee compensation. If the amount in this box is SE income, report it on Schedule C or F (Form 1040) if a sole proprietor or on Form 1065 and Schedule K-1 (Form 1065) if a partnership, and the recipient/partner completes Schedule SE (Form 1040).
Box 1b. Shows the total amount of cash tips. “Cash tips” include tips received in cash or charged. This amount has been included in the amount reported in box 1a. Use the amount in box 1b when determining the qualified tip deduction in Part II of Schedule 1-A (Form 1040).
Box 1c. Shows up to two Treasury Tipped Occupation Code(s) (TTOC) for your tipped occupation(s). Use this code(s) in determining the deduction for qualified tips in Part II of Schedule 1-A (Form 1040). If the occupation code 000 is used, and no other code is included in box 1c, your cash tips are not qualified tips; do not use the amount reported in box 1b for the deduction for qualified tips.
Box 1d. Shows the total amount of qualified overtime compensation. This amount has been included in the amount reported in box 1a. Use the amount in box 1d when determining the qualified overtime compensation deduction in Part III of Schedule 1-A (Form 1040).
Note: If you are receiving payments on which no income, social security, and Medicare taxes are withheld, you should make estimated tax payments. See Form 1040-ES (or Form 1040-ES (NR)). Individuals must report these amounts as explained in these box 1 instructions. Corporations, fiduciaries, and partnerships must report these amounts on the appropriate lines of their tax returns.
Box 2. If checked, consumer products totaling $5,000 or more were sold to you for resale on a buy-sell, a deposit-commission, or another basis. Generally, report any income from your sale of these products on Schedule C (Form 1040).
Box 3. Shows your total compensation of excess golden parachute payments subject to a 20% excise tax. See your tax return instructions for where to report.
Box 4. Shows backup withholding. A payer must backup withhold on certain payments if you did not give your TIN to the payer. See Form W-9, Request for Taxpayer Identification Number and Certification, for information on backup withholding. Include this amount on your income tax return as tax withheld.
Boxes 5–7. State income tax withheld reporting boxes.
Future developments. For the latest information about developments related to Form 1099-NEC and its instructions, such as legislation enacted after they were published, go to www.irs.gov/Form1099NEC.
Free File Program. Go to www.irs.gov/FreeFile to see if you qualify for no-cost online federal tax preparation, e-filing, and direct deposit or payment options.
The Instructions for Recipient from the official form (December 2026 revision), printed on Copy B by the generator.
What is the 1099-NEC threshold for 2026?
$2,000. Report nonemployee compensation once the total you paid one person in 2026 reaches $2,000, counting every payment, not each one separately. The minimum applies to tax years beginning after 2025 and may be adjusted for inflation beginning in 2027. Other payment types have their own minimums in the 1099 threshold table.
When is Form 1099-NEC due?
For 2026 payments, both copies are due by February 1, 2027: Copy B to the contractor and Copy A to the IRS, whether you file on paper or electronically. The date already moves a weekend deadline to the next business day, as the IRS general instructions allow.
Can I print a 1099-NEC myself?
Yes for the contractor's copies, no for the IRS copy. The printable Copy B and Copy 2 are recipient copies, and IRS Publication 1179 allows payers to print their own substitute recipient statements when they carry the same information as the official form. That is what this generator makes.
Copy A cannot be printed from a PDF, because the IRS scans it. File it through IRIS, which is free, or on the official red paper form, which you can order from the IRS. If you file 10 or more information returns in total, you must e-file.
What the recipient copies must include
Publication 1179 lists what a substitute Copy B needs: the tax year, form number and name together, and the payer's name, address, TIN and a phone number.
They also need the recipient's details, the box captions with Federal income tax withheld in bold, the Copy B legend and the recipient instructions. The PDF here includes all of them.
Correcting a 1099-NEC
Sent a form with a mistake? Tick Corrected form in the generator, enter the right figures and give the contractor the new Copy B. File the corrected Copy A the way you filed the original, through IRIS or on paper. The general instructions cover each type of error.
1099-NEC or 1099-MISC?
Pay for a contractor's services goes on the 1099-NEC. Rent, royalties, prizes and attorney settlement proceeds go on the 1099-MISC. The 1099 generator compares both forms box by box and switches between them without losing your entries.
Sources and review
Reviewed by M. Humza against the official sources below, last checked October 22, 2026. The figures, dates and box captions on this page and in the generator are read from the same data file.
- IRS Form 1099-NEC (Rev. December 2026), including Instructions for Recipient
- Instructions for Forms 1099-MISC and 1099-NEC (12/2026)
- IRS Publication 1179 (Rev. July 2026), substitute recipient statements (section 4.1.3 and 4.4.2)
- General Instructions for Certain Information Returns, due dates on a Saturday, Sunday or legal holiday
- IRS, E-file information returns with IRIS (free portal for Forms 1099-NEC and 1099-MISC, corrections)
- IRS, About Form W-9 (the payee gives its TIN to the payer that files an information return)
- IRS, Order paper information returns and employer returns (official scannable forms)
- General Instructions for Certain Information Returns (2025, the latest edition), Guide to Information Returns: amounts to report for Forms 1099-B (all amounts), 1099-C ($600 or more), 1099-DIV and 1099-INT ($10 or more), 1099-G ($10 or more for refunds and unemployment), 1099-R ($10 or more), 1099-S (generally $600 or more), 1099-SA (all amounts), and statements to recipients by January 31, or February 15 for Forms 1099-B and 1099-S
This page is general information about Form 1099-NEC, not tax advice. For your own situation, check the IRS instructions or ask a tax professional.