Free 1099 Generator: 1099-NEC and 1099-MISC for 2026
A 1099 generator fills in the recipient copies of Form 1099-NEC or 1099-MISC for payments your business made. This free 1099 form generator is fillable online: choose the form, enter the payer, the recipient and the amounts, and download printable Copy B and Copy 2 with the IRS instructions.
Reviewed by M. Humza. Checked against the IRS sources October 22, 2026. Fill in the form
Contractor or freelancer fees of $2,000 or more: 1099-NEC. Rent, prizes or other income of $2,000 or more, or royalties of $10 or more: 1099-MISC. Every payment type.
This makes the copies you give the recipient. File Copy A through the free IRS IRIS portal or on the official scannable form. Paid as a contractor? Your 1099 comes from the business that paid you.
What is Form 1099?
Form 1099 is a family of IRS information returns. A business uses Form 1099-NEC or 1099-MISC to report certain payments it made during the year to someone who is not its employee. It gives the recipient a copy, files Copy A with the IRS, and the recipient uses it to report the income.
What do I need to make a 1099?
- Your business name, address and telephone number. The phone number is required on the recipient's copy.
- Your taxpayer identification number: your EIN, or your SSN if you have no EIN.
- The recipient's name, address and TIN, from their Form W-9. Their copies show only the last four digits.
- What you paid them in 2026, by type of payment, and any federal or state tax you withheld.
- Your state payer number, if you withheld state tax.
Which 1099 do I need: NEC or MISC?
Use Form 1099-NEC when you paid someone who is not your employee $2,000 or more for services in 2026, including attorneys' fees. Use Form 1099-MISC for rent, prizes, other income and medical payments of $2,000 or more, royalties of $10 or more and gross proceeds paid to an attorney of $600 or more.
| You paid | Form | Report when you paid at least |
|---|---|---|
| A contractor, freelancer or other non-employee for services | 1099-NEC, box 1a | $2,000 |
| Attorneys' fees for legal services | 1099-NEC, box 1a | $2,000 |
| Rent for business property or equipment | 1099-MISC, box 1 | $2,000 |
| Royalties | 1099-MISC, box 2 | $10 |
| Prizes, awards and other income | 1099-MISC, box 3 | $2,000 |
| Medical and health care services | 1099-MISC, box 6 | $2,000 |
| Substitute payments in lieu of dividends or tax-exempt interest (brokers) | 1099-MISC, box 8 | $10 |
| Settlement proceeds paid to an attorney | 1099-MISC, box 10 | $600 |
| Wages to an employee | Form W-2, not a 1099 | On Form W-2 instead |
Each amount is the total you paid one person during 2026, not each payment. The $2,000 minimum applies to tax years beginning after 2025 and may be adjusted for inflation beginning in 2027. The IRS Instructions for Forms 1099-MISC and 1099-NEC cover every box and exception.
Lawyers, card payments, corporations and rent paid through a property manager each have their own rule. 1099-NEC vs 1099-MISC sorts those cases payment by payment, with a worked year for one small business.
Boxes on the two forms, side by side
| What it reports | 1099-NEC box | 1099-MISC box |
|---|---|---|
| The main amount | 1a Nonemployee compensation | 1 Rents, 2 Royalties, 3 Other income, 6 Medical and health care payments, 10 Gross proceeds paid to an attorney and others |
| Cash tips (new for 2026) | 1b, included in 1a | 13a, included in 3 |
| Tipped occupation code, TTOC (new for 2026) | 1c | 13b |
| Qualified overtime pay (new for 2026) | 1d, included in 1a | 14, included in 3 |
| Federal income tax withheld | 4 | 4 |
| Direct sales of consumer products for resale (checkbox) | 2 | 7 |
| State tax withheld, state number, state income | 5 to 7 | 16 to 18 |
Box captions are from the December 2026 revisions of both forms. Box-by-box detail is on the 1099-NEC generator and 1099-MISC generator pages.
New boxes on the 2026 forms
Form 1099-NEC now has box 1b for cash tips, 1c for the tipped occupation code and 1d for qualified overtime pay. Each amount is already included in box 1a. Form 1099-MISC has the same items in boxes 13a, 13b and 14, included in box 3. Leave them blank unless they apply.
When are 1099s for 2026 due?
Form 1099-NEC is due to the recipient and to the IRS by February 1, 2027. Form 1099-MISC is due to the recipient by February 1, 2027 and to the IRS by March 1, 2027 on paper or March 31, 2027 electronically.
| Form | To the recipient | To the IRS |
|---|---|---|
| 1099-NEC | February 1, 2027 | February 1, 2027, paper or electronic |
| 1099-MISC | February 1, 2027 (February 16, 2027 with box 8 or 10) | March 1, 2027 on paper, March 31, 2027 electronically |
Dates already move weekend and holiday deadlines to the next business day, as the IRS general instructions allow.
How do I issue a 1099?
- Collect a W-9 first, before you pay a contractor or payee. The Form W-9 gives you their name and TIN. If they do not give you a TIN, you generally must backup withhold and report it in box 4, whatever the amount.
- Total the year. Add up what you paid each person in 2026, by type of payment.
- Make the recipient copies in this 1099 creator for everyone at or over the threshold for that payment type in the table above.
- Send Copy B by the deadline, by mail or electronically with the recipient's consent.
- File Copy A through IRIS, or on official paper forms with Form 1096.
Example: a 1099-NEC for a freelance illustrator
Peachtree Design Studio LLC, a design studio in Atlanta, paid a freelance illustrator, Jordan Rivera, 4,850.00 over several invoices in 2026. It also paid a freelance copywriter 1,200.00. Neither had tax withheld.
The illustrator's total is over the $2,000 minimum, so the studio gives them a 1099-NEC with 4,850.00 in box 1a and files Copy A. The copywriter's total is under the minimum, so no 1099-NEC is required for them.
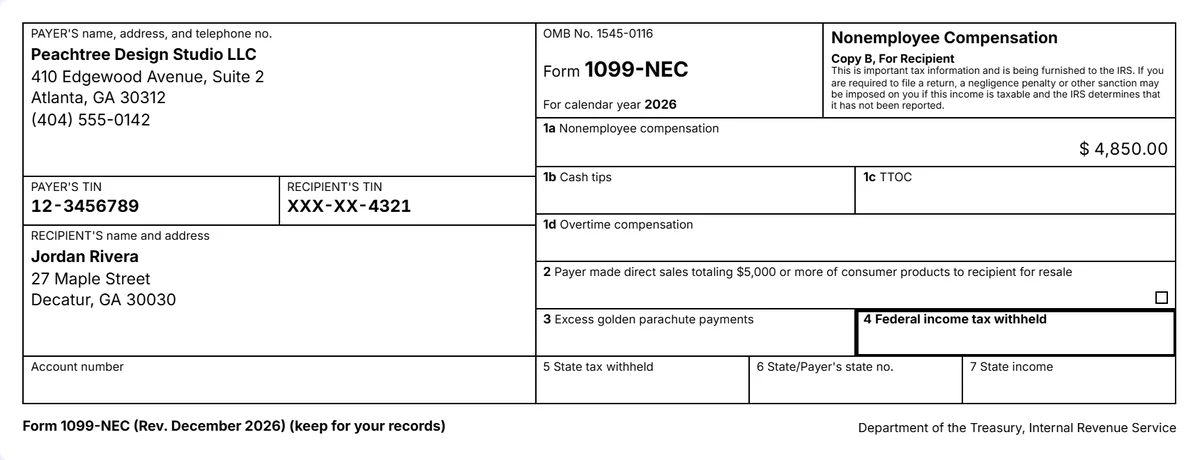
The copies follow IRS Publication 1179 for substitute recipient statements: black ink, the official box captions and legends, the recipient's TIN shown as the last four digits, and the recipient instructions taken from the official form by script.
Can I file a Copy A that I print myself?
No. Copy A goes to the IRS through IRIS or on the official scannable paper form, which you can order from the IRS. The IRS cannot scan a Copy A printed from a PDF or a generator.
Copy B, Copy 2 and the other black copies can be printed for the recipient, and those are the copies this generator makes. If you file 10 or more information returns in total, you must file them electronically.
Who can make a 1099?
Only the business or person that made the payments. A payer may prepare the recipient copies itself, as long as they match what it files with the IRS. A contractor who was paid does not make their own 1099: it comes from the business that paid them.
Contractors who want a record of payments they received can use the 1099 earnings statement, which is a personal record, not a Form 1099.
Corrections, corporations and state filing
Found a mistake after sending a form? Tick Corrected form in the generator, enter the right amounts and send the recipient a new Copy B.
File the correction with the IRS the same way you filed the original, through IRIS or on paper. The IRS General Instructions for Certain Information Returns cover each type of error.
Payments to corporations are generally exempt from 1099 reporting. Exceptions include attorneys' fees, gross proceeds paid to an attorney and medical and health care payments: report them even to a corporation. The payee's W-9 tells you whether they are a corporation.
Late, missing or incorrect forms can each draw an IRS penalty, and the amount grows the later you file. The current penalty amounts are in the general instructions. Many states also want the 1099 data, some through the IRS Combined Federal/State Filing Program and others directly, so check your state's rules.
Sources and review
Reviewed by M. Humza against the official sources below, last checked October 22, 2026. The figures, dates and box captions on this page and in the generator are read from the same data file.
- IRS Form 1099-NEC (Rev. December 2026), including Instructions for Recipient
- IRS Form 1099-MISC (Rev. December 2026), including Instructions for Recipient
- Instructions for Forms 1099-MISC and 1099-NEC (12/2026)
- IRS Publication 1179 (Rev. July 2026), substitute recipient statements (section 4.1.3 and 4.4.2)
- General Instructions for Certain Information Returns, due dates on a Saturday, Sunday or legal holiday
- IRS, E-file information returns with IRIS (free portal for Forms 1099-NEC and 1099-MISC, corrections)
- IRS, About Form W-9 (the payee gives its TIN to the payer that files an information return)
- IRS, Order paper information returns and employer returns (official scannable forms)
- IRS, Understanding your Form 1099-K (report all income whether or not you receive a form)
- General Instructions for Certain Information Returns (2025, the latest edition), Guide to Information Returns: amounts to report for Forms 1099-B (all amounts), 1099-C ($600 or more), 1099-DIV and 1099-INT ($10 or more), 1099-G ($10 or more for refunds and unemployment), 1099-R ($10 or more), 1099-S (generally $600 or more), 1099-SA (all amounts), and statements to recipients by January 31, or February 15 for Forms 1099-B and 1099-S
- IRS, Understanding your Form 1099-K: payment apps and online marketplaces report payments for goods or services over $20,000 in more than 200 transactions; gifts and repayments from friends and family are not reported
This page is general information about the forms, not tax advice. For your own situation, check the IRS instructions or ask a tax professional.